Original title: SLG Accounts for Nearly 50% of Overseas Revenue! How Are Gaming Giants Pivoting After the MMO Decline?
Author: DataEye Research Institute
Source: DataEye Game Watch
Hero image via Pexels
For some time, MMORPGs have been a major source of revenue for Chinese game companies. But as a once-mature category begins to feel growth pressure, whether game companies can build their next growth curve through new products, new markets and new technologies has become a key question for the industry.
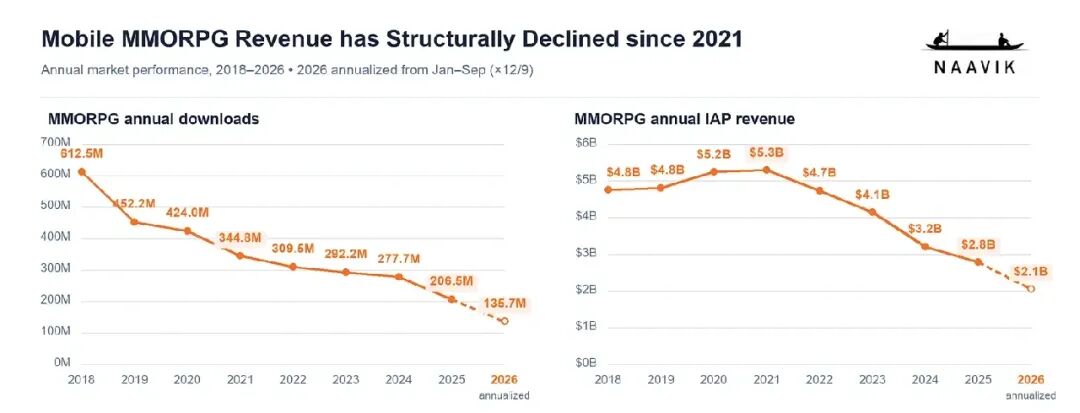
According to Naavik's analysis of the global mobile gaming market, between 2021 and 2025 global mobile MMORPG in-app purchase revenue fell from $5.3 billion to $2.8 billion, down about 47% in four years; downloads dropped from 345 million to 206 million over the same period, a fall of about 40%. This does not mean every MMORPG has lost its market, but the overall contraction of the category does make the growth model that relies on a few evergreen titles much more challenging.
At the same time, SLG and mini-games are showing different market opportunities. According to the 2025 China Game Industry Report, strategy games accounted for 49.96% of revenue among the top 100 Chinese self-developed mobile games by overseas revenue in 2025, while domestic mini-program game market revenue reached RMB 53.535 billion, up 34.39% year on year. With the traditional strength category under pressure on one side and other tracks still creating new increments, game companies’ business layouts are shifting accordingly.
Seen from this angle, the industry change is not one category simply replacing another, but the growth logic of different tracks diverging. MMORPGs still have evergreen products and IP operation value, but companies can no longer bet all their growth on a single product type. How to reuse existing R&D, publishing and monetization capabilities while entering new categories and markets has become the question leading players must answer.
MMO giants’ transformation endgame: mid-to-light SLG?
Taking 37 Interactive Entertainment and Century Huatong as examples, the business layouts of leading companies are reflecting how China’s gaming industry is searching for new growth curves. But if we broaden the view from a single company to the whole industry, what companies face is not a simple category choice, but a comprehensive test across product life cycles, market headroom and operational capability.
37 Interactive Entertainment: from operating mature MMO products to parallel SLG and mini-game layouts
In the past, MMORPG was undoubtedly an important label for 37 Interactive Entertainment, and it remains part of its product portfolio today. In January 2026, the company's self-developed Ragnarok Online: World Tour launched in Hong Kong, Macao and Taiwan and topped the free and grossing charts of major local app stores. Classic IP can still provide user recognition and market foundation for new products, but IP value does not equal a guarantee of success: how to refresh gameplay while preserving players' nostalgia, adapt to user habits in different regions, and extend the product life cycle through sustained operations remains key to product performance.
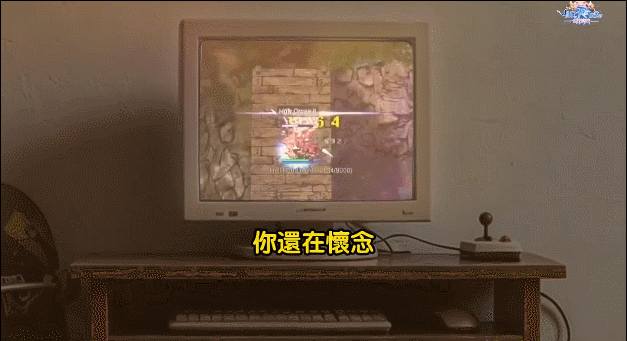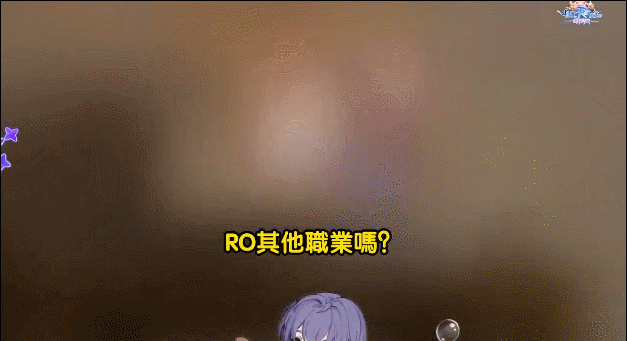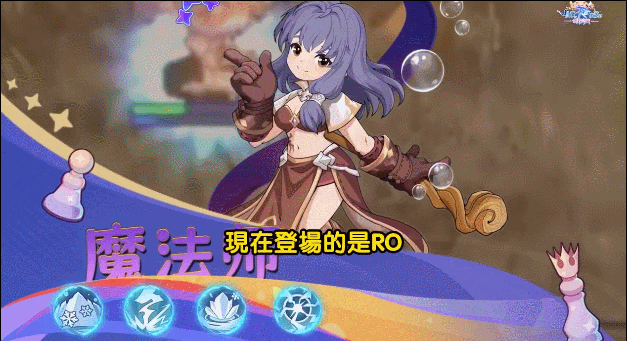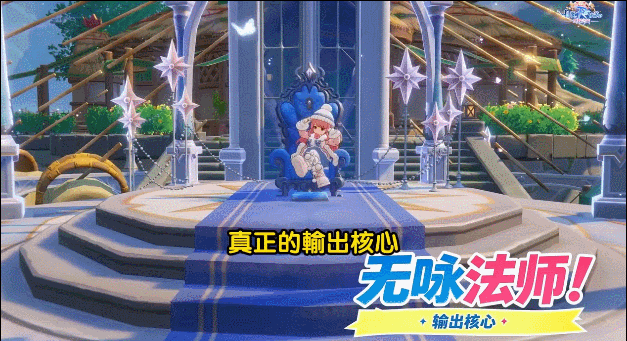
Creative showcase of Ragnarok Online: World Tour ad creatives in the Hong Kong, Macao and Taiwan markets (via ADX Overseas)
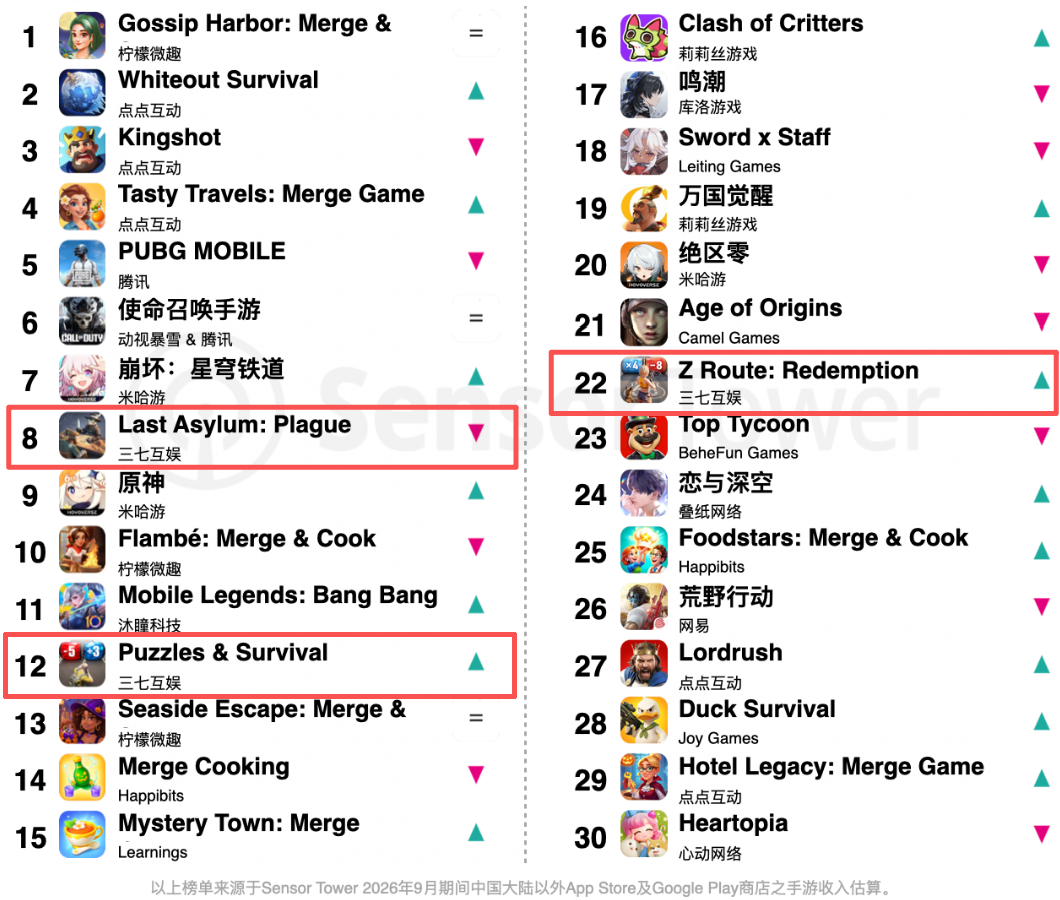
Second, SLG overseas expansion is moving from accumulated mature titles to a relay of new launches. In Sensor Tower's September 2026 Top 30 Chinese mobile games by overseas revenue, 37 Interactive Entertainment had three SLG titles on the list.
Puzzles & Survival, with stable performance, has surpassed 75 million cumulative users and RMB 16.8 billion in cumulative revenue since launch through mid-2026, long providing 37 Interactive Entertainment with overseas SLG operating experience; meanwhile, Last Asylum: Plague, whose overseas revenue exceeded $26 million in September to hit a new high, and Z Route: Redemption, which entered the chart for the first time, offer a window into its future growth capability.
For SLG, blending themes and gameplay can help products reach a wider audience, but what really determines long-term performance is whether a product can build stable social relationships, continuously update content, and strike a balance between user acquisition cost and user life cycle value.
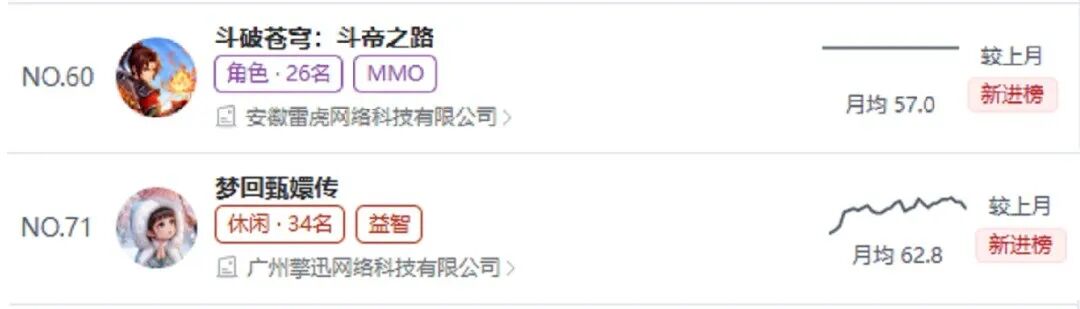
Third, mini-games provide 37 Interactive Entertainment with another path for continuous output. According to ADX data, in the October 2026 WeChat Mini Game Top 100 chart, 37 Interactive Entertainment had eight products listed, including mature titles with established player bases such as Seek Tao Da Qian, Survival 33 Days and Dream Weaving Forest, as well as newly listed games like Battle Through the Heavens: Emperor of Fighting Road and Dream Back to Legend of Zhen Huan.
37 Interactive Entertainment's mini-game offerings are no longer confined to a single type, but span different IPs, themes and gameplay directions. This reflects its shift from a single-hit-driven model toward sustainable multi-product supply through diverse category layout, continuous new launches, and publishing and operations capabilities.
As a result, 37 Interactive Entertainment is forming a product portfolio that runs MMORPG, SLG and mini-games in parallel. The monetization rhythms of different categories differ: some MMORPG titles, backed by mature IPs and existing user bases, may generate revenue faster; SLG titles usually need longer tuning and operating cycles before building long-term returns. Neither is absolutely better or worse — what matters is whether a company can make products with different life cycles and business models complement each other.
Century Huatong: using different business units to capture different growth opportunities
Century Huatong's business layout reflects another path of diversification: different business units within the group take on different growth missions. Shengqu Games has long operated classic IPs such as The Legend of Mir and Dragon Nest, while Diandian Interactive has built an overseas product portfolio centered on SLG and extending into casual games.
Aion: Wilds, co-developed by Shengqu Games and South Korea's NCsoft
Century Huatong's 2026 semi-annual report shows that the company's internet gaming business generated RMB 21.342 billion in revenue in the first half, up 29.87% year on year. Among this, Diandian Interactive and Century Games together contributed RMB 18.441 billion. Whiteout Survival set a new high three years after launch and topped the global mobile game revenue chart in June 2026; Kingshot has long ranked in the top three of Chinese mobile games by overseas revenue. The significance of the two flagship SLG titles goes beyond revenue scale: they demonstrate the ability of Chinese companies to build product advantages in fiercely competitive overseas markets through long-term operations, continuous iteration and global publishing.
Notably, Century Huatong has not confined its growth opportunities to a specific category. In Sensor Tower's September 2026 Top 30 Chinese mobile games by overseas revenue, five Century Huatong games made the list — three SLG titles and two casual games. The strong performance of merge games such as Travel & Feast and Hotel Story means a mature overseas publishing and operations system can potentially be reused across different categories rather than relying entirely on a single track.
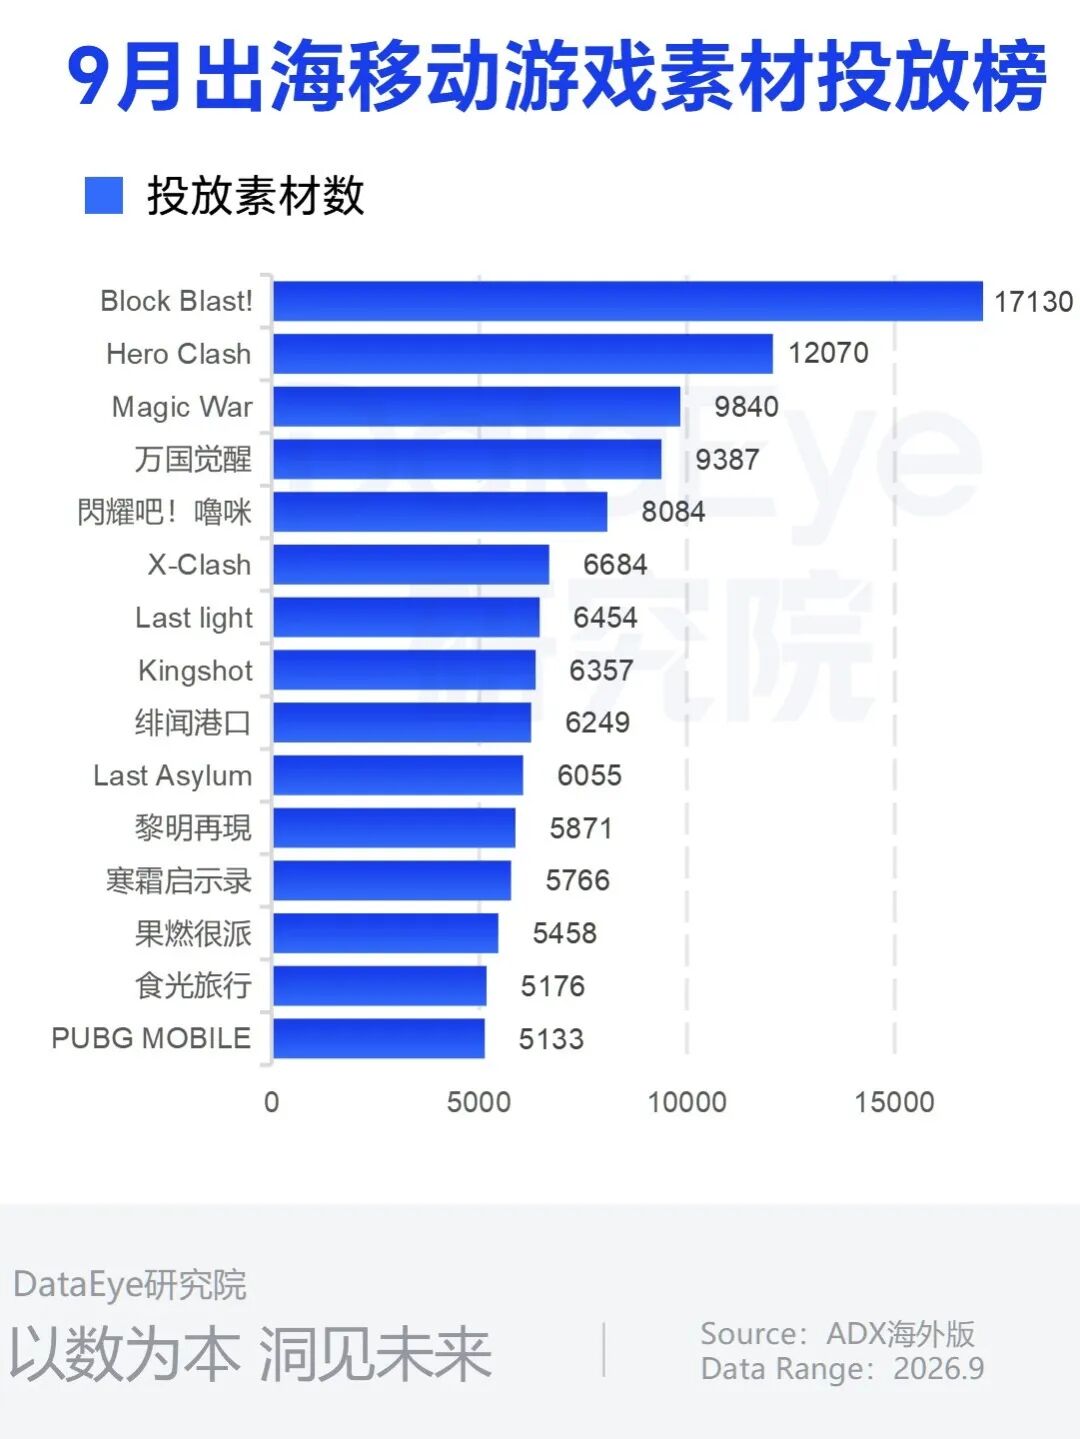
ADX data shows Travel & Feast entered the top list of overseas game ad spending in September
At the group level, Century Huatong is not steering all business units toward the same category; instead, through business division, traditional IP operations and overseas SLG and casual games complement each other. This also suggests that transformation does not necessarily mean an existing team collectively changes its R&D direction — it may also mean reallocating resources within the group so that traditional businesses and new growth engines coexist.
The common ground between the two companies lies here: moving from reliance on a single product or category to multi-product portfolios; from single-market operations to differentiated layouts at home and overseas; and from launching new games to continuously reusing R&D, publishing, monetization and long-term operations capabilities.
Why can SLG take on growth, and why is it not a simple answer to transformation?
SLG has become an important revenue source for Chinese companies going overseas, which is related to its long-term operations and monetization model. But for companies shifting from MMORPG to SLG, the category change brings not only gameplay adjustments, but also changes in the pace of product development, market validation and revenue release.
MMORPG relies on mature IPs, existing user recognition and a relatively clear progression system; some titles can accumulate users quickly at launch and enter a relatively stable operating phase early. SLG, by contrast, depends more on continuous content iteration, alliance social systems, competitive mechanics and long-term goal building; products often need a longer tuning and user accumulation process before their long-term value is gradually unlocked.
This difference also means transformation cannot be judged by short-term performance after launch. For SLG, the early stage requires validating theme, gameplay and user acquisition efficiency; the mid-term requires improving retention through version iteration and social ecosystem building; only later can companies rely on player relationships, ongoing content and monetization design to form more stable revenue.
User acquisition can help a product reach users, but it cannot replace product polish and long-term operations. Therefore, expanding from MMORPG to SLG is both a migration of product capability and a re-adaptation of operating rhythm: R&D and operations teams need to allow enough room for validation and growth, while continuously assessing the relationship between retention, monetization performance and acquisition cost.
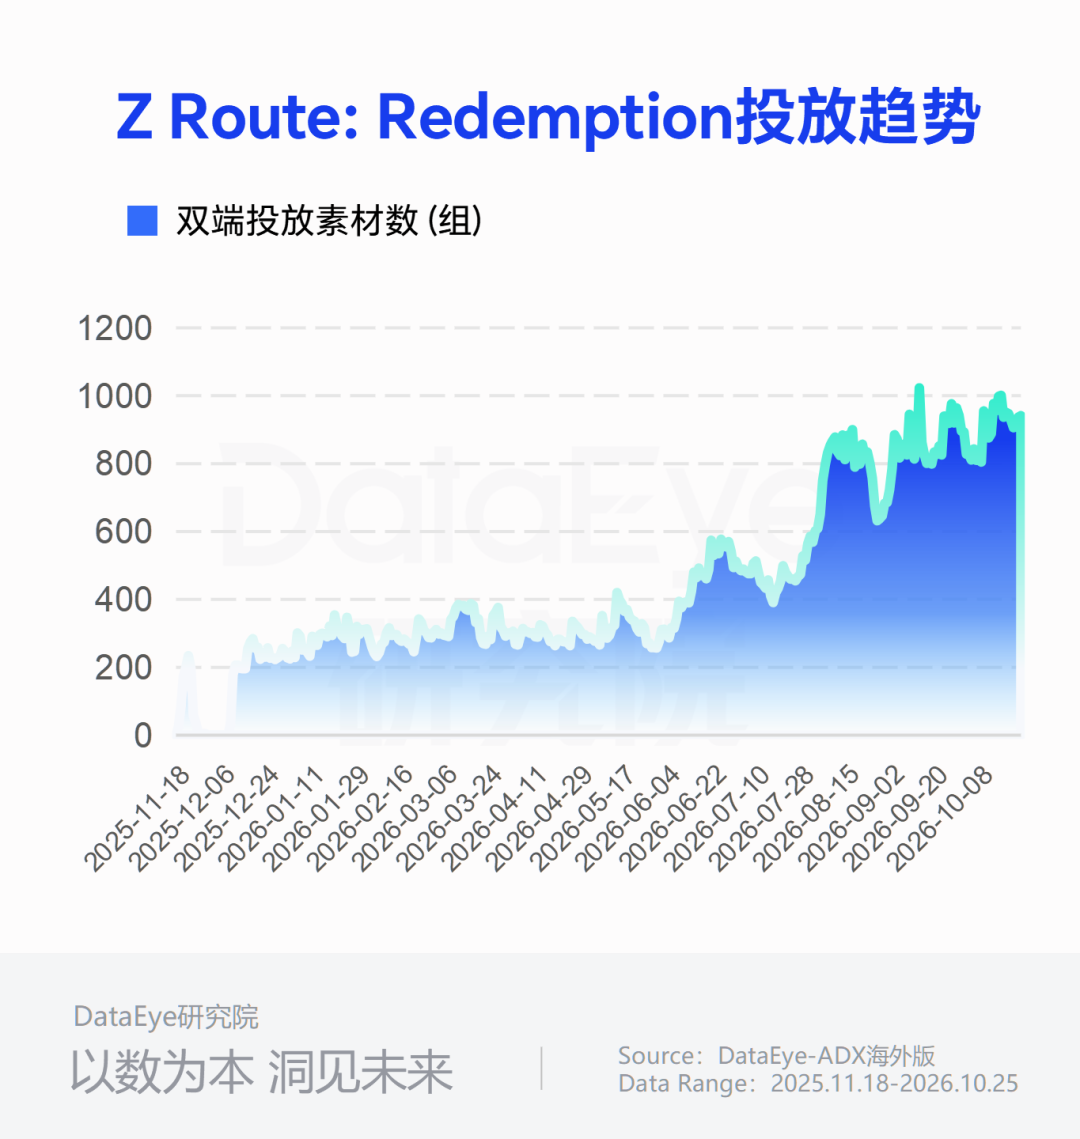
ADX Overseas shows Z Route significantly increased its ad spending in August this year, successfully lifting the game’s commercial performance; but the tuning and polish in its earlier phase was the key foundation for product quality
Industry data suggests SLG's market headroom deserves attention, but it does not mean transformation can be quickly replicated as success. The 49.96% revenue share of strategy games among the top 100 self-developed mobile games by overseas revenue reflects the revenue structure of top overseas titles, not the general performance of all overseas games.
For companies building SLG portfolios, what really matters is not only whether new titles can spike revenue in the short term, but whether they can gradually complete product tuning, accumulate stable users, and establish sustainable long-term operations and monetization capabilities. Different categories have different growth cycles, and the results of transformation should be observed within the corresponding product cycle.
Giants' transformation in progress: the next direction is AI
If SLG and mini-games represent game companies’ growth exploration in product categories and markets, then AI may further change how companies produce games, acquire technology and create content. For game companies, AI does not point in just one direction: it can enter existing R&D and marketing processes, may give rise to new content forms, and can also help companies connect with external technology resources through investment.
AI is reshaping the game production chain
At present, the most easily observable value of AI in the game industry remains productivity gains. Art assets, video ads, text localization, customer service and user acquisition often involve large amounts of repetitive work that suits models and automation tools to boost output efficiency.
This change has grown from experiments by individual companies into R&D and operations layouts of leading game companies. Entering 2026, companies such as NetEase and Tencent have successively disclosed AI applications in their game businesses — NetEase noted that AI has been integrated into art, design, programming, animation and QA processes in game development, and applied to dynamic interactive gameplay in some titles; Tencent also said in its 2026 full-year performance materials that AI is accelerating its game content production, improving user experience and raising marketing efficiency. AI’s application in gaming is thus extending from single-point efficiency gains such as asset generation toward R&D production, in-game interaction and user operations.
But productivity gains are only the first step. More asset output does not necessarily mean higher asset quality; lower generation costs do not mean R&D costs for an entire game fall proportionally. Whether AI can further shorten product iteration cycles, improve ad campaign ROI and let teams spend more time on gameplay innovation is what determines its commercial value.
AI may give rise to new product forms
If productivity is AI's direct impact on the game industry, then changes in content forms may bring longer-term imagination.
As video generation, real-time interaction and dynamic narrative technologies develop, the boundary between games and film/TV content may blur further. AI video can lower the production threshold for some visual content, while language models may make character dialogue, story branches and mission feedback more flexible. For game companies with interactive design experience, this opens space for exploring interactive film games, AI-native narratives, and the fusion of games with short-drama content.
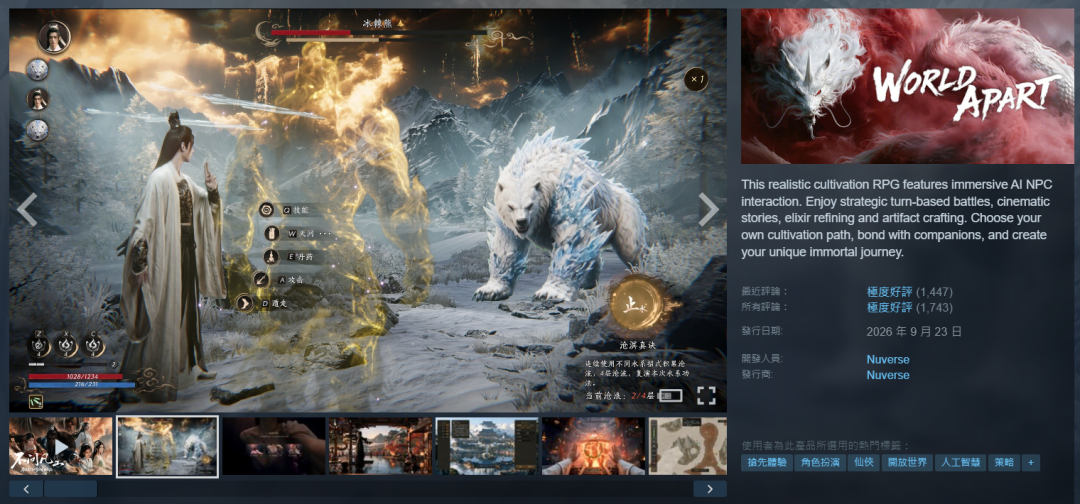
Bu Wen Fan Chen, an interactive film game developed by ByteDance's Jiangnan Studio, entered the Steam top 20 bestseller chart after launch; its Early Access version is estimated to have generated RMB 7-8 million in total revenue in the first three weeks
Investment capability becomes another trump card in the AI era
The changes brought by AI are also reflected in how game companies acquire technology capabilities.
In the past, game companies’ outward investment revolved around the traditional industry chain — game R&D teams, IPs, publishing channels and so on. But as AI, robotics, computing infrastructure and other technologies develop rapidly, more and more listed game companies are extending their investment maps beyond the core gaming business.
DataEye Research Institute's earlier statistics show that since 2025, 15 mainstream listed game companies have participated in 72 investment and financing projects with total investment exceeding RMB 87.2 billion, with large amounts flowing into frontier technology fields such as AI and robotics. Game companies' investment logic is expanding from simply seeking the next game product toward layouts in underlying technologies and potential new industry opportunities.
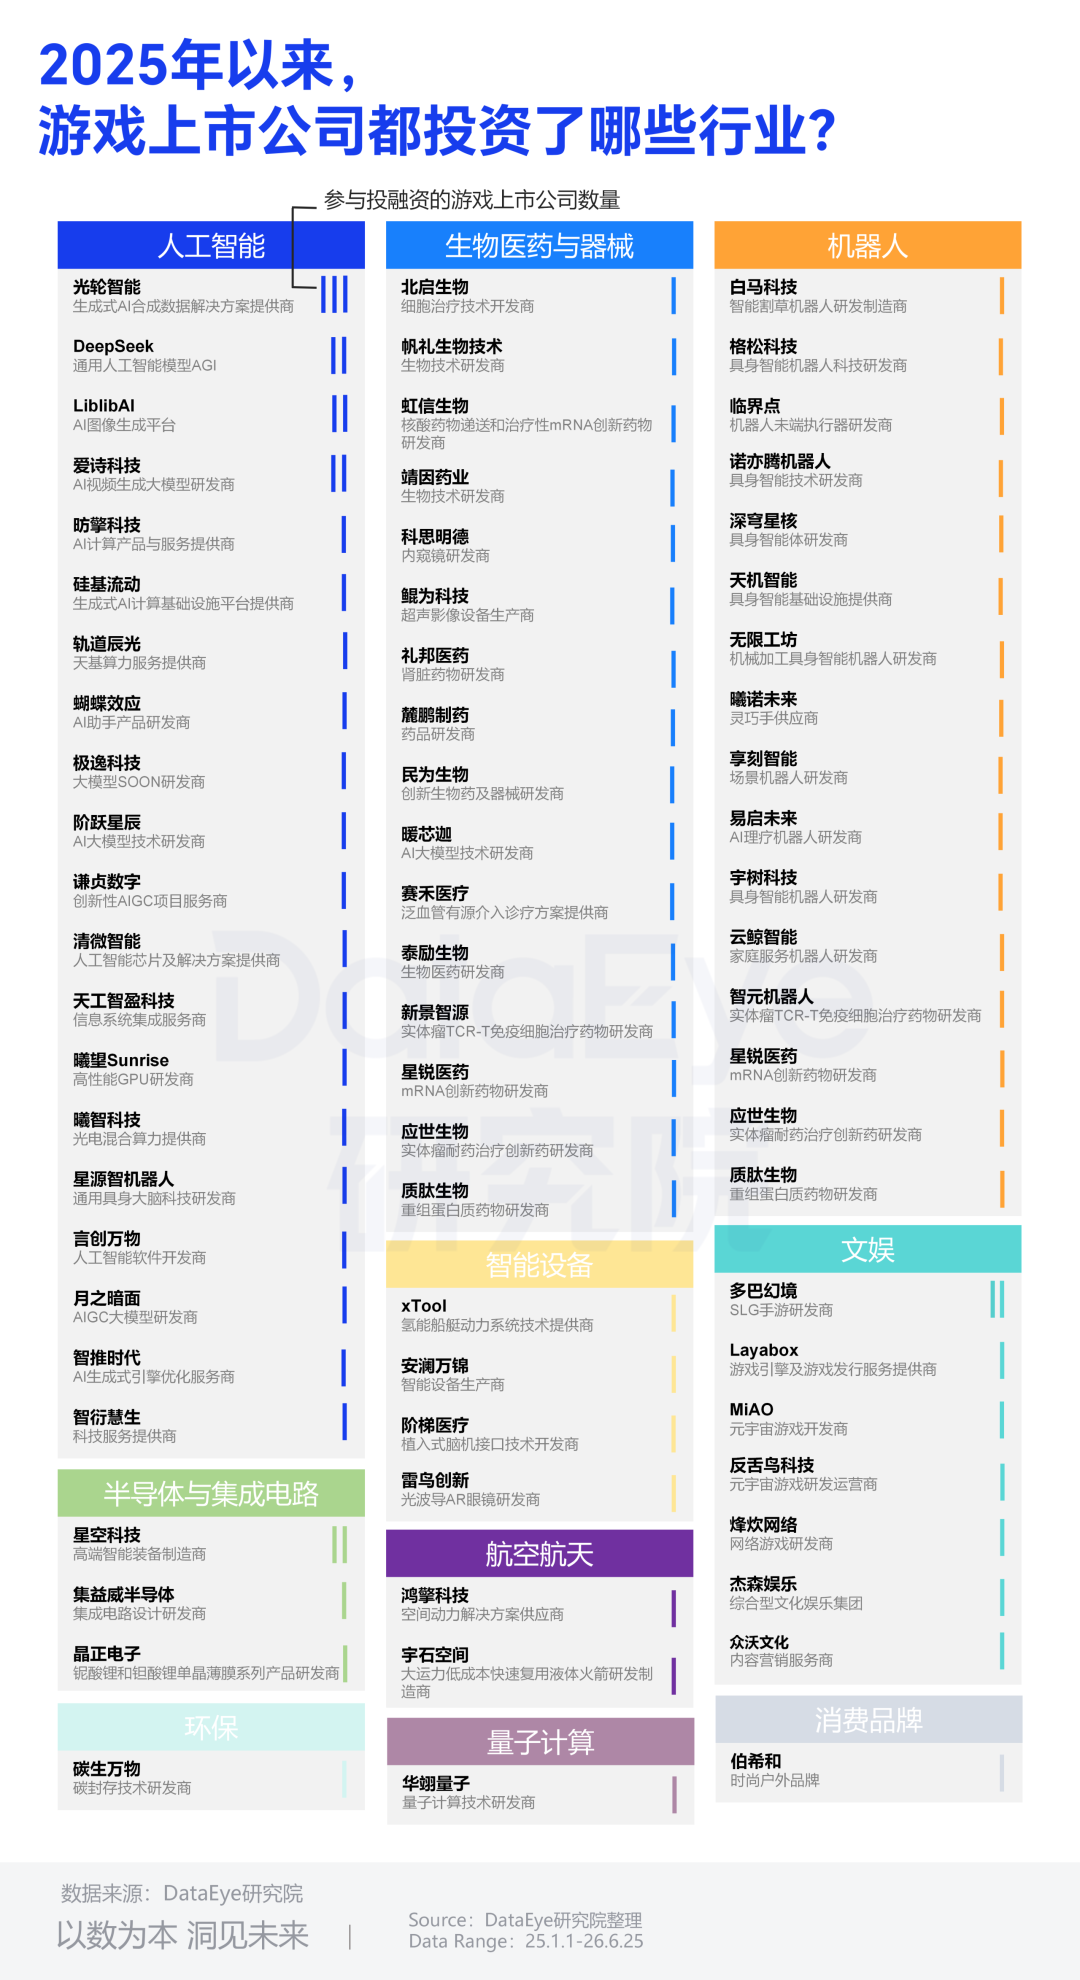
From this perspective, game companies' investment capability is becoming another competitive edge worth watching in the AI era.
Self-developed models and tools test a company’s internal technology accumulation, while investment provides a path to connect with external innovation resources. Especially for companies with capital strength, publishing and monetization experience, investment may bring not only financial returns but also help them identify technology directions earlier, build partnerships, and reserve room for future business innovation.
Conclusion: growth curves are not singular, and neither are competitive capabilities
From MMORPG to SLG, mini-games and then AI, the changes at game companies are not simply chasing the next hot trend, but reallocating R&D, publishing, market and technology resources when growth in existing businesses comes under pressure.
While continuing to operate MMORPGs, 37 Interactive Entertainment is advancing SLG overseas expansion, mini-game layout and AI capability building; Century Huatong's case shows traditional IP operations and overseas growth engines can coexist. The two companies are not taking identical routes, but both reflect a trend: corporate competitiveness increasingly depends on the ability to build diversified product portfolios and let R&D, publishing, monetization and technology capabilities keep working across different businesses.
AI adds another variable in this process. It may raise productivity in existing businesses, give rise to new content forms, and influence how companies acquire technology through investment layouts. However, whether it is SLG, mini-games or AI, none should be treated as a surefire growth answer just because of market heat.
Track layout decides where companies look for growth, while AI capability may affect how efficiently, at what cost, and to what degree of innovation capability they pursue it. In a fast-changing market, what truly matters for game companies is not betting on a single trend, but building the ability to continuously identify opportunities, validate products and realize commercial value.